Full Coverage vs. Total-Loss: What’s the Difference for International Moving Insurance?
Marine insurance on an international move usually comes down to one of three choices: full coverage, a more limited total-loss option, or declining coverage with a signed waiver. The right one depends mostly on one decision you make earlier in the process: whether your goods are professionally packed or self-packed. As an FMC-licensed door-to-door moving company, here’s how the options actually differ.
Full Coverage: The Broader Option
Full coverage, sometimes called all-risk coverage, protects your shipment against loss or damage from a wide range of causes during transit: handling damage, water exposure, and most accidents during loading, transport, or unloading. It requires professional packing, since the insurer needs confidence in how items were protected before they’ll cover damage to them. This is the option most clients choose for a full household shipment, particularly one that includes furniture, electronics, or anything not easily replaced.
What “All-Risk” Doesn’t Actually Cover
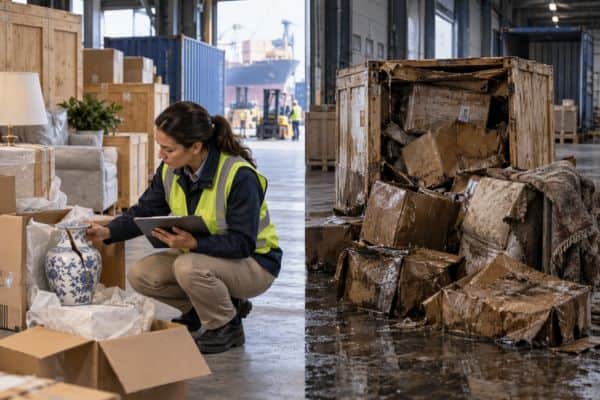
“All-risk” is a bit of a misleading name, and it’s worth understanding what it actually excludes, since these exclusions are standard across the marine cargo insurance industry, not specific to one carrier. Inherent vice, damage from the natural characteristics of an item rather than anything that happened to it in transit, isn’t covered: a wine collection that spoils from its own chemistry, or wood that cracks from properties it already had, falls into this category. Ordinary wear and tear on items that were already old or worn before shipping isn’t covered either; insurance protects against transit damage, not pre-existing condition. Delay itself is excluded too, even when the delay is caused by something otherwise covered, so lost use of an item while it sits at a port isn’t a claimable loss on its own. And insufficient packing is excluded when the insured did the packing themselves, which is the same reason self-packed goods only qualify for the more limited total-loss option in the first place.
Total-Loss Coverage: What It Actually Covers
Total-loss coverage is significantly more limited than full coverage, and the name is a fairly accurate description: it generally applies when a shipment is lost entirely, such as a container going overboard or a total destruction event, rather than covering individual item damage. This is the option available for self-packed goods and vehicles, since an insurer can’t verify how something was protected inside a box they didn’t pack. If you’re packing your own boxes to save on cost, it’s worth understanding upfront that you’re also accepting a narrower insurance option, not the same coverage at a lower price.
Why Self-Packed Goods Don’t Qualify for Full Coverage
This isn’t a policy designed to push clients toward paying for professional packing. Insurers price coverage based on verifiable risk, and a box packed by a trained crew using consistent materials and techniques is a known quantity; a box packed at home with whatever materials were on hand is not, no matter how carefully it was done. That’s the actual reason for the distinction, not a sales tactic.
Declining Coverage
You can decline insurance coverage entirely, which requires a signed waiver acknowledging that your shipment travels uninsured. This is sometimes chosen for shipments of low-value items where the insurance premium doesn’t make financial sense relative to what’s being shipped, but it means you’d have no recourse for loss or damage during transit.
Rates and What Actually Determines Your Cost
Insurance cost scales with your shipment’s declared value and which coverage type you choose. Because rates and exact terms can change, we send clients the actual insurance application to review rather than quoting a number that might not reflect current terms by the time you ship. Reviewing the real document, not a general description, is the only way to know exactly what’s covered and what your specific rate will be.
If You Need to File a Claim
Document damage as soon as you notice it, ideally with photos taken before you move or discard anything, and note it on the delivery paperwork at the time of unloading rather than after the crew has left. A claim filed with clear photo evidence and prompt documentation moves faster than one reconstructed from memory weeks later. Your coordinator can walk you through the specific claims process for your policy, since the documentation required can vary by coverage type.
Frequently Asked Questions
If I pack most boxes myself but have professionals pack my fragile items, what coverage applies?
Coverage is typically determined item by item based on who packed it, so professionally packed fragile items can qualify for full coverage while self-packed boxes fall under the more limited total-loss option. Confirm the specifics with your coordinator when you book your move.
Does total-loss coverage mean a single damaged item isn’t covered at all?
Generally, yes, that’s the core difference from full coverage. Total-loss coverage is built around the shipment being lost entirely, not individual item damage. Read the actual policy terms for your specific situation, since this is exactly the kind of detail worth confirming before you decide.
Is jewelry covered under standard shipment insurance?
High-value items like jewelry often need separate documentation or a specific rider rather than falling under standard coverage automatically. Flag any high-value items to your coordinator so they’re properly documented and covered.
If my shipment is delayed at a port, is that covered by insurance?
No. Delay is excluded under standard marine cargo insurance even when the delay itself is caused by something otherwise covered, like a port hold or customs issue. Insurance covers physical loss or damage to your goods, not the inconvenience or cost of a longer timeline.
Ready to Review Your Coverage Options?
We’ll send you the actual insurance application so you can review current rates and exact terms before you decide. Learn more about our insurance coverage or request a quote to get started.